Storm season can change the value of a parked car overnight. Along the Gulf Coast, hurricane rain can flood a driveway. Across Texas, Oklahoma, and Colorado, hail can batter vehicles in minutes. In California and other Western states, fast-moving wildfires can destroy cars before their owners can move them. So does comprehensive coverage protect your car from natural disasters?
Usually, yes. Comprehensive auto insurance generally covers direct vehicle damage from floods, hail, wind, falling objects, wildfires, and other severe-weather events. But coverage must be active when the damage occurs, and deductibles, exclusions, and settlement rules still matter.
What Comprehensive Coverage Actually Pays For
Comprehensive coverage, sometimes called “other than collision,” protects your vehicle against many losses that do not involve a traffic collision. It differs from liability insurance, which pays for covered damage you cause to others, and collision insurance, which typically handles crashes with vehicles or objects.
The distinction matters during storms. A tree blown onto your parked car is normally a comprehensive claim. If you lose control on a rain-soaked road and strike a tree, collision coverage generally applies. Understanding comprehensive vs. collision insurance helps prevent expensive assumptions.
How Insurance Responds to Different Natural Disasters
Flooding and Hurricane Storm Surge
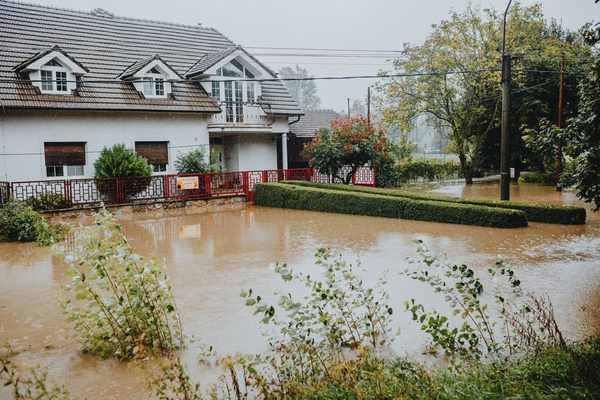
Flood damage car insurance is typically provided through the comprehensive portion of your auto policy. It generally includes rising water, flash floods, and hurricane storm surge, subject to policy terms. You do not normally need a separate residential flood policy to protect your vehicle; homeowners flood insurance addresses different property.
Water can destroy wiring, computers, upholstery, and mechanical systems, even without obvious exterior damage. Insurers may declare deeply flooded vehicles total losses because hidden corrosion and electrical problems make repairs impractical. Never start a submerged car just to test it. Photograph the waterline and arrange professional inspection.
Hailstorms and Severe Thunderstorms
In the central United States, hail damage insurance is especially relevant during spring and summer. Comprehensive coverage commonly pays for dented panels, broken glass, and other covered hail damage. Repairs may involve paintless dent removal, replacement glass, or conventional bodywork, depending on the severity.
If a storm is approaching, move your car into a garage or sturdy shelter when safe. Avoid parking beneath trees with weak branches; protection from hail offers little comfort if the branches fall.
Hurricanes, Tornadoes, and Windblown Debris
A hurricane car insurance claim can involve several causes of loss. Wind may hurl debris into the windshield, a falling branch may crush the roof, or floodwater may reach the cabin. Comprehensive coverage commonly responds to these events. Crashing while evacuating, however, would ordinarily involve collision insurance.
Do not assume a hurricane deductible from your homeowners policy automatically applies to your car. Home and auto policies are separate contracts. Check the comprehensive deductible and any special provisions shown on your auto policy.
Wildfires and Lightning
Comprehensive coverage generally includes direct damage caused by fire and lightning. If a wildfire burns your vehicle, the insurer may pay for repairs or settle a total loss. Smoke or ash damage needs closer review because payment depends on actual physical damage and the wording of your policy; ordinary cleaning is not automatically covered.
Drivers in wildfire-prone regions should preserve vehicle photographs and ownership records before evacuation season. Always follow official evacuation orders rather than risking personal safety to move a vehicle.
What Natural Disaster Claims May Not Cover
Comprehensive insurance is broad, not unlimited. It ordinarily does not cover routine mechanical breakdown, gradual deterioration, or the costs of a collision. Existing damage and losses that happened before the policy took effect are not newly insured. The fact that bad weather contributed to a crash does not necessarily make it a comprehensive claim.
Rental reimbursement is usually separate optional protection. Check whether you have it before assuming the insurer will provide a replacement vehicle while yours is repaired.
How Much Would the Insurer Pay?
For repairable damage, an approved comprehensive claim typically pays the covered repair amount minus your deductible. Suppose hail causes $4,000 in covered damage and your deductible is $500. The insurer would generally pay $3,500, leaving you responsible for $500.
If the vehicle is totaled, the payout is usually based on its actual cash value immediately before the disaster, minus the applicable deductible. That can be substantially less than a brand-new replacement costs. If the settlement is lower than your outstanding loan balance, optional GAP protection may help, depending on its terms. Learning about car insurance deductibles and total-loss valuations before disaster season makes these figures less surprising.
A Pre-Storm Check That Can Prevent a Costly Surprise
Imagine a Houston driver who recently dropped comprehensive coverage from a paid-off car to reduce premiums. A tropical storm floods the street, and water destroys the car’s engine and electronics. A liability-only policy ordinarily will not pay for the owner’s vehicle. Adding comprehensive afterward cannot retroactively cover the damage.
Well before serious weather arrives, examine your declarations page. Confirm that comprehensive is listed for the right vehicle, review the deductible, and check the effective dates. Ask about restrictions on adding coverage near a major storm; some insurers temporarily limit changes in threatened areas.
Save photographs showing the car’s condition and mileage, and keep your insurer’s claim number accessible during evacuations or power outages. These steps help establish the condition of the vehicle before a loss.
How to File a Claim After a Natural Disaster
Once the area is safe, take photographs from several angles. Include waterlines, broken windows, fallen branches, and the surrounding scene. Report the damage promptly through your insurer’s approved channel, describe the event, and ask whether an adjuster must inspect the vehicle before repairs or towing.
Keep receipts for authorized emergency expenses and notes of every conversation. Do not drive a flood-damaged car or attempt electrical repairs without professional guidance. Following widespread disasters, inspections may take longer, so request your claim number and next steps in writing.
If a settlement seems too low, ask for the valuation or repair estimate and provide evidence about the vehicle’s mileage, features, condition, and comparable local prices. You can also consult your state insurance department about claim-handling concerns.
Frequently Asked Questions
Does comprehensive insurance cover a car flooded in a hurricane?
Generally yes, if coverage was active when the flood occurred and no relevant exclusion applies. The deductible and total-loss terms affect the payout.
Will liability-only insurance pay for hail damage?
No. Liability coverage does not ordinarily repair your own hail-damaged car. Comprehensive coverage is normally needed.
What if a tornado drops a tree on my car?
A falling tree striking your vehicle is generally a comprehensive loss. Driving into a fallen tree usually falls under collision coverage instead.
Can I add comprehensive insurance once a storm is forecast?
You can ask your insurer, but companies may restrict changes as major storms approach. Coverage must be effective before the loss occurs.
Prepare Before the Weather Turns Dangerous
Comprehensive coverage for natural disasters can mean the difference between paying a deductible and losing the full value of a car. The best time to review protection is before flood alerts, hail warnings, or evacuation orders. Check your policy, understand the deductible, and move your vehicle out of harm’s way when it is safe.